


This post was co-written with Andy Beach, author of Engines of Change.
We decided to collaborate because our methods are complementary. Andy reads the floor. I read the data.
We approached NAB Show 2026 independently and landed on the same signal without coordinating. That convergence is what brought us together.
The progress of agentic AI in Media Tech has been fast, faster than most (me included) anticipated. But what I find more striking is that agentic AI is emerging as one of the clearest manifestations of a broader structural trend in the media technology industry: the growing importance of the control layer.
This is something both Andy and I have been circling from different angles. And it shows up in different places: from the language vendors use to the architecture of the products being launched. This piece is an attempt to pull these threads together into a single thesis ahead of IBC 2026, with agentic AI as the protagonist of the control story.
Our readings of NAB Show 2026
Let’s start with some background, and with the most recent major show on the industry calendar.
I was not at NAB Show 2026. Andy was. Yet, we arrived at the same conclusion independently, and using entirely different methods.
Andy spent five days reading the floor. What follows is his account, in his words.
I have been walking NAB since 1996, and the most reliable signal at any show is the gap between what vendors say publicly and what they tell you in the private roadmap conversation. This year that gap ran in an unusual direction. The public language was AI features. The private conversations were about wiring. Vendors wanted to talk about where their system would sit in a customer’s stack, what it would coordinate, what data it would hold, and what other tools would have to route through it. Booth after booth was pitching for position in the same layer, even when nobody named it.
That layer is the substrate. The models on display were largely interchangeable and the vendors knew it. What they were actually selling was the connective tissue around the models, the permissions and policies and workflow state and audit trails that decide what an AI system is allowed to do inside a media operation. Beneath the AI announcements, the floor was selling control infrastructure.
I ran a word frequency and co-occurrence analysis across written product announcements from 148 exhibitors. The headline finding: the top word was control, co-occurring most with IP. AI came sixth, behind cloud and IP, despite most post-show coverage treating NAB as an AI event.
A floor read and a corpus analysis, conducted independently, finding the same signal in the noise of the show floor.
Why control? As broadcast and media infrastructure has grown increasingly distributed over recent years, the governance question has become the dominant anxiety in the sector. And, as the NAB Show text analysis showed, the answer vendors keep proposing is the same: consolidation into a single platform. But before getting there, let’s dig a little deeper into the corpus data.
Zooming in: what AI products say that others don’t
Andy and I thought it would be helpful to run a follow-up analysis to my NAB Show study focused specifically on AI product announcements (roughly 21% of the total sample, with over a third of those concentrated in West Hall) to see whether AI products tell a different story from the broader corpus. And they do.
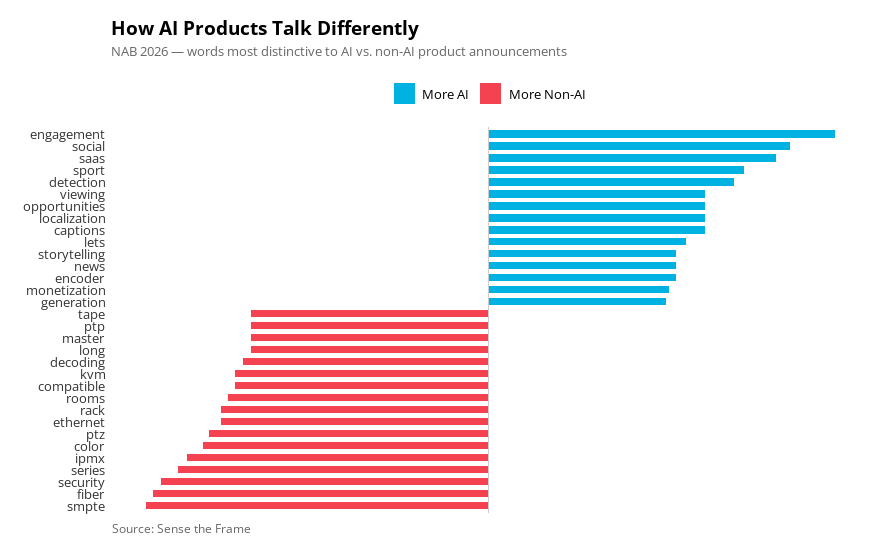
AI products cluster around: engagement, social, sport, detection, viewing, localization, captions, storytelling, news, monetization. Non-AI products cluster around: tape, SMPTE, fiber, rack, ethernet, PTZ, decoding, KVM, IPMX.
AI product language is about audiences, content and outputs. Non-AI product language is about hardware, signals and standards.
This divergence is telling. AI products live at the application layer: engagement, discovery, monetization, storytelling. Non-AI products live at the infrastructure layer: fibre, rack, ethernet, rooms. Control sits in the middle. Some of that split reflects category composition, since hardware vendors rarely rewrite their marketing copy, but the layering it exposes is real. And, if you look more closely, agentic AI is one of the key areas where that control layer is being built.
Agentic AI: three signs of control
Since October 2025, Sense the Frame has been tracking agentic AI product launches across the broadcast and media technology sector. The tracker now covers 14 products launched across IBC 2025 and NAB Show 2026. Three signals emerge from the tracker when read through the lens of the control thesis. One caveat travels with all three. The tracker measures what vendors announce, which is supply. It tells us what the industry wants to sell. Whether buyers run these systems in production is a different question, and it is the one IBC needs to answer.
Agentic AI is concentrating where control matters most. Applications such as content discovery and advertising have dominated the tracker, and not by coincidence. Discovery is a pattern-recognition problem at scale; agents outperform manual workflows precisely because the volume of content exceeds human capacity to govern it. Advertising is a high-frequency, data-driven environment where campaign variables change faster than human teams can process. In both cases, agents operate within parameters set by humans.
Trust and guardrails are becoming key product requirements. At IBC 2025, governance mechanisms were mainly differentiators. By NAB Show 2026, they appear in almost every agentic AI product. Some examples. Amagi’s Newspulse embeds a policy engine that enforces editorial guardrails throughout the content generation process. Dalet Dalia preserves human override at every step of its orchestration layer. Cuez’s open framework allows broadcasters to deploy models locally where data governance requires it. Trust is being embedded into media workflows.
Orchestration is how control is operationalized. Vendors are increasingly building coordination layers that adapt general-purpose models and components (often provided by big technology platforms) through domain knowledge and proprietary data. At NAB Show 2026 Veritone launched Discovery Content Intelligence with VERI, which relies on multi-model cognitive design, orchestrating multiple specialized models, with each handling discrete tasks. At IBC 2025, Accedo and ContentWise had already positioned their UX products as coordination layers for multiple AI components rather than standalone tools.
This last shift is perhaps the biggest, as it is repositioning products as single platforms replacing point solutions. And it extends beyond agentic. According to my tracker, orchestration language across NAB Show product announcements more than doubled from 2025 to 2026, independently of the agentic AI category.
This is a clear architectural (and business) strategy. Orchestration layers are stickier than point solutions. The single platform the language data showed vendors selling is, in many cases, an orchestration layer with control built in. And in an era where underlying capabilities are increasingly commoditized, orchestration is becoming one of the few remaining levers of differentiation.
There is a question buried in that pitch that buyers should be asking. Consolidation into a single platform means consolidation into someone’s platform. Whoever owns the orchestration layer owns the policies, the routing decisions, and the record of what happened, and those assets do not commoditize the way models do. The durable value in this transition is accruing to governance and infrastructure while the capability layer gets cheaper underneath everyone at roughly the same speed. The single platform pitch is a bid for that position.
The deal data points the same way. Orchestration is starting to appear as acquisition logic, with companies buying their way into the coordination layer rather than assembling point capabilities.
The clearest recent example in MediaTech is Foundry’s acquisition of Griptape in February 2026: an AI orchestration platform bought specifically to coordinate AI workflows inside Nuke and Foundry’s broader VFX pipeline. These are few other examples from different industry segments:
In March 2026, Kaltura acquired PathFactory, adding journey intelligence and dynamic orchestration of personalised engagement paths to its video platform.
In June 2025, Audinate acquired Iris Studio. This is a networking platform company buying a control layer product to govern its own device ecosystem.
In April 2025, LiveU acquired Actus Digital, adding an intelligence and control layer across its contribution ecosystem.
And the big players are no exception. In June 2026, OpenAI acquired Ona to: “bringing its secure cloud execution and orchestration technology into our rapidly expanding Codex ecosystem.”
When product strategy and M&A strategy converge on the same layer, that is usually where an industry believes its margin will live.
What IBC 2026 will test
The language vendors used at NAB Show prioritized control. The products being launched embed governance as a requirement and orchestration as the dominant architecture.
Agentic AI is, so far, the clearest expression of the control story. Vendors are no longer selling just capability; they are selling the layer that governs it.
IBC 2025 was when agentic AI arrived as vendor language. IBC 2026 is when we find out whether it becomes an operating layer, and that is a testable question. We will be watching for buyer deployments on the floor rather than staged demos. We will be watching for agents from different vendors coordinating with each other, because an operating layer that only orchestrates its own components is a walled garden with better marketing. We will be watching for standards activity around agent interoperability and provenance, and for pricing that bills like infrastructure rather than like a feature. If those signals show up, the control thesis holds. If the floor is still language and demos, then agentic AI remains a story vendors are telling about themselves. Andy will read the floor. I will update the trackers. Either way, we will publish the verdict.
Look out for the next installment in this series, coming out after IBC 2026.
